In the Czech Republic, businesses can register for Full Czech VAT (Plátce DPH) or Light VAT (Identifikovaná osoba).
The difference is simple: Full Czech VAT payers charge VAT on taxable Czech sales and can deduct VAT on eligible business purchases. Light VAT holders do not charge VAT on ordinary Czech sales but must pay Czech VAT on certain foreign purchases and report qualifying EU transactions.
Full Czech VAT vs. Light VAT: Comparison
Situation | Full Czech VAT (Plátce DPH) | Light VAT (Identifikovaná osoba) |
|---|---|---|
Registration | Mandatory after exceeding Czech turnover thresholds, or voluntary | Required when providing B2B services to EU companies or purchasing foreign services subject to Czech VAT
|
Czech turnover threshold | CZK 2,000,000 / CZK 2,536,500 | No minimum turnover for EU B2B services or foreign services subject to Czech VAT |
Czech invoices | Charges VAT on taxable Czech sales | Does not charge VAT on ordinary Czech sales |
VAT deduction on purchases | Yes, for eligible business purchases | No |
Invoicing EU business clients | Reverse charge for B2B services under the standard rule | Reverse charge for B2B services under the standard rule |
Purchasing foreign services | Declares Czech VAT and can deduct it on eligible purchases | Declares and pays Czech VAT without deduction |
1. What Is Full Czech VAT (Plátce DPH)?
Full Czech VAT registration makes a business a VAT payer in the Czech Republic.
VAT payers charge VAT on taxable Czech sales, submit regular VAT returns, and deduct VAT on eligible business purchases.
When Is Full Czech VAT Registration Mandatory?
Since 1 January 2025, Czech VAT registration thresholds have been calculated using turnover during the calendar year, not the previous 12 consecutive months.
Two thresholds apply in 2027.
When You Must Register for Czech VAT in 2027
Czech turnover | When VAT payer status begins |
|---|---|
Exceeds CZK 2,000,000 | 1 January of the following calendar year, unless earlier registration is elected |
Exceeds CZK 2,536,500 | The day after exceeding the threshold |
Businesses must submit their VAT registration application within 10 working days after exceeding either threshold.
For example, if your Czech turnover exceeds CZK 2,536,500 on 15 June, you become a VAT payer on 16 June. You must also submit your registration application within the legal deadline.
Your VAT obligations begin on the date set by law, even if you have not completed the registration paperwork.
Businesses can also apply for voluntary Full Czech VAT registration before reaching these thresholds.
The tax authority can request contracts, invoices, or other documents confirming that the business is operating.
These rules are covered by §§ 4a, 6 and 94 of the Czech VAT Act and explained in the Czech Financial Administration’s VAT registration guidance.
Real Client Case: CZK 5 Million in Income Without Czech VAT Registration
Pexpats prepared an annual tax return for a freelancer who earned more than CZK 5 million from providing services to an American-registered company.
After reviewing the tax return, the Czech tax authority noticed that the freelancer’s income exceeded CZK 2 million. The authority contacted Pexpats to check if the freelancer should have registered for Full Czech VAT.
We explained that the income came from B2B services supplied to an American company and did not count toward Czech VAT turnover. Pexpats prepared an affidavit and submitted the client’s invoices to confirm the source of income.
After reviewing the documents, the tax authority confirmed that the freelancer did not need Full Czech VAT registration based on this income. The client continued operating without Full Czech VAT.
A freelancer can earn more than CZK 2 million from foreign business clients without becoming a Full Czech VAT payer. Income from ordinary B2B services supplied to companies outside the Czech Republic does not count toward Czech VAT turnover.
The affidavit was requested to clarify this client’s situation. Freelancers do not need to submit an affidavit simply because they work with foreign companies.
Why was Full Czech VAT registration not required?
Under § 9(1) of the Czech VAT Act, the place of supply for ordinary B2B services is where the business customer is established. Because the freelancer provided these services to an American company, their place of supply was outside the Czech Republic.
Under § 4a, services supplied outside the Czech Republic do not count toward Czech VAT turnover. Therefore, the CZK 5 million earned from these services did not trigger mandatory Full Czech VAT registration under § 6.
Legal References
§ 9(1) — Place of supply for B2B services. For ordinary B2B services, the place of supply is where the business customer is established. In this case, the customer was based in the United States.
§ 4a — Czech VAT turnover calculation. Income from these services did not count toward Czech VAT turnover because the services were supplied outside the Czech Republic.
§ 6 — Mandatory Czech VAT registration. The registration thresholds apply to Czech turnover, not total worldwide income. Therefore, the CZK 5 million earned from the American company did not trigger mandatory Full Czech VAT registration.
View the law: Czech VAT Act — Act No. 235/2004 Coll.
Real Client Case: What Happens When You Miss the Czech VAT Threshold?
Pexpats prepared an annual tax return for a freelancer who provided services to a Czech-registered company.
The freelancer had not been monitoring his Czech turnover. By the end of the year, he had earned more than CZK 3 million from providing these services without registering for Full Czech VAT.
After reviewing his tax return, the Czech tax authority contacted Pexpats about the missing VAT registration. We arranged the freelancer’s VAT registration.
However, the freelancer had continued invoicing the Czech company without VAT even after he was required to become a VAT payer. As a result, he had to pay VAT on the services provided after his VAT obligations began, despite not having charged VAT to his customer.
Monitor Your VAT Threshold
In 2027, exceeding CZK 2,536,500 in Czech turnover makes you a VAT payer from the following day.
If you continue invoicing clients without VAT after becoming a VAT payer, you still have to pay VAT on those services. Monitoring your Czech turnover is very important to avoid unexpected VAT payments.
Free Invoice Generator with Smart VAT Monitoring
Pexpats Invoice Generator is a completely free invoicing application developed and maintained by Pexpats since 2021 for freelancers and businesses in the Czech Republic. It includes a personal account with secure login, invoice storage, customer management, and automated business tools.
Your total income is not necessarily your Czech VAT turnover. That’s why Pexpats Invoice Generator includes smart VAT monitoring that checks your invoices based on your customers’ locations, including Czech, EU, and non-EU clients. Instead of simply adding up all your invoices, it calculates the income that counts toward Czech VAT registration thresholds and alerts you when you reach them.
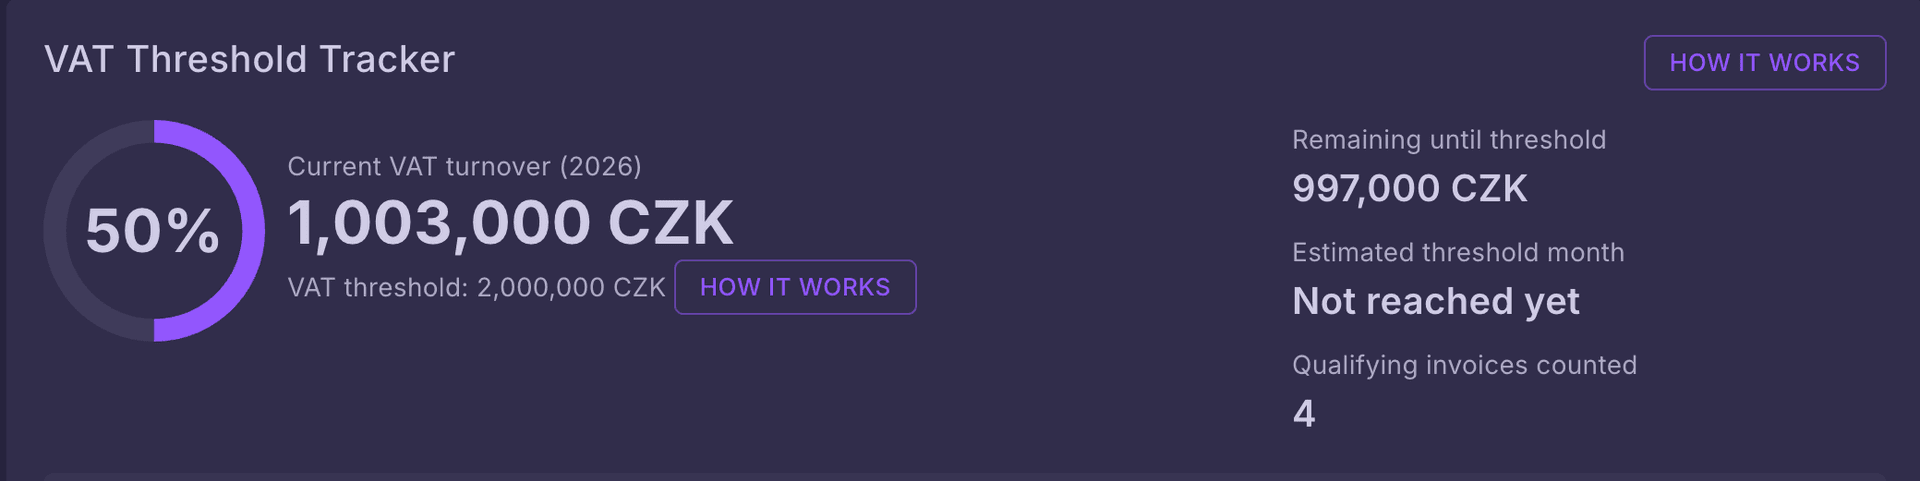
Other features include:
Invoice management — Store invoices, customer details, and invoicing history.
Automated reminders — Track tax deadlines, payment deadlines, and unpaid invoices.
Invoice templates and exchange rates — Create invoices with automatic exchange rate support.
Multilingual invoicing — Application available in Czech and English, with invoices in 16 languages and over 20 currencies.
All features are completely free, with no subscription required.
2. What Is Light VAT (Identifikovaná osoba)?
Light VAT (Identifikovaná osoba) is a VAT registration for Czech freelancers and businesses that provide services to EU business clients or purchase services from foreign companies.
Unlike Full Czech VAT, Light VAT holders do not charge VAT on ordinary Czech sales and cannot deduct VAT on business purchases.
There is no minimum income threshold for Light VAT registration when providing EU B2B services or purchasing foreign services subject to Czech VAT. Even a freelancer earning CZK 100,000 annually may need to register.
When Is Light VAT Registration Mandatory?
A Czech freelancer or business that is not registered for Full Czech VAT must register for Light VAT when it:
Provides services to EU businesses — For example, a Czech freelancer invoicing a German company for consulting or IT services under the standard B2B rule.
Purchases services from foreign companies — For example, Google Ads, software subscriptions, or Airbnb platform commissions subject to Czech VAT.
Purchases goods from other EU countries — When purchases exceed the CZK 326,000 registration threshold.
What Is the Light VAT Registration Deadline?
You must submit your Light VAT registration application within 15 days after the registration obligation begins.
This deadline is established by § 97 of the Czech VAT Act.
Light VAT Registration Can Cover Earlier Invoices
At Pexpats, we often see EU business clients refusing to pay freelancers until their Czech VAT number is registered. At the same time, the Czech tax authority may ask for proof of payment to confirm that the services were provided.
This creates a problem: the client is waiting for VAT registration, while the tax authority is asking for proof of payment.
If you face this situation, remember that your Light VAT registration can start before you receive confirmation from the tax authority.
For example, a freelancer completes work for a German company on 20 November. Pexpats submits the registration application, but the tax authority confirms registration on 2 December.
If the registration requirement began on 20 November, the registration starts from 20 November, not 2 December.
Your EU client should know that waiting for the registration confirmation does not change the original registration date.
What Is the CZK 326,000 EU Goods Threshold?
If your purchases of goods from other EU countries exceed CZK 326,000 in the current calendar year, Light VAT registration becomes mandatory. Purchases in the previous calendar year also affect whether the threshold applies.
This threshold applies to EU goods purchases, not foreign services such as Google Ads.
The rules are covered by §§ 2a and 6g of the Czech VAT Act.
Real Client Case: Three Years of Unpaid VAT on Airbnb Commissions
A Czech Airbnb accommodation provider contacted Pexpats for help after receiving a notice from the Czech tax authority about missing Light VAT registration and three years of unpaid VAT.
The client had been operating his accommodation business since 2023. He had a registered Czech business, an IČO, and a Czech tax identification number (DIČ), but did not know that Light VAT registration was required.
Why was Light VAT registration mandatory?
Airbnb provides accommodation businesses with services such as advertising their properties, connecting them with guests, and managing bookings. In return, Airbnb charges the accommodation provider a commission.
These services are supplied by an Airbnb company registered in another EU country to a business registered in the Czech Republic.
Under the reverse charge rules, the Czech business receiving these services must register for Light VAT (unless already registered for Full VAT) and calculate and pay Czech VAT on Airbnb’s commissions.
The client had been receiving these services for three years without registering for Light VAT or paying Czech VAT on the commissions.
After discovering the missing registration and unpaid VAT, the Czech tax authority contacted the client.
The client then contacted Pexpats to resolve the problem.
We reviewed the client’s Airbnb records for all three years, prepared the outstanding VAT declarations, calculated the total Airbnb commissions for each period, and calculated the Czech VAT owed on those commissions.
This allowed the client to declare and pay the outstanding VAT for the full three-year period.
VAT is calculated on Airbnb’s commissions, not the client’s total accommodation revenue.
For example, if you receive CZK 100,000 in accommodation revenue through Airbnb and Airbnb charges you CZK 10,000 in commissions, you must calculate and pay 21% Czech VAT on the CZK 10,000 commission.
This means paying CZK 2,100 to the Czech tax authority under the reverse charge rules, not VAT on your full CZK 100,000 accommodation revenue.
3. Practical Examples: Full Czech VAT vs. Light VAT
Example: Buying a Laptop from Alza
You purchase a laptop from a Czech retailer for your business.
The laptop costs CZK 24,200 including VAT.
Buying a CZK 24,200 Laptop — VAT Comparison
Item | Full Czech VAT | Light VAT |
|---|---|---|
Laptop price excluding VAT | CZK 20,000 | CZK 20,000 |
VAT at 21% | CZK 4,200 | CZK 4,200 |
Total paid | CZK 24,200 | CZK 24,200 |
Cost after VAT deduction | CZK 20,000 | CZK 24,200 |
A Full Czech VAT payer can deduct CZK 4,200 when the laptop is used entirely for business activities that allow VAT deduction but the Light VAT holder cannot deduct the VAT, so the laptop costs CZK 4,200 more.
Pexpats VAT Calculator
Use the Pexpats VAT Calculator to:
Add VAT to an amount excluding VAT.
Calculate VAT included in a total price.
Calculate Czech VAT at 21% or 12%.
Enter your amount to see the calculation.
Online Czech VAT Calculator
4. How Do VAT Reporting Obligations Differ?
Full Czech VAT Reporting
Full Czech VAT payers submit regular VAT returns, including returns for periods with no sales or VAT payable. These are called nil VAT returns.
They also submit:
VAT control statements (Kontrolní hlášení) for Czech transactions that must be reported.
EU summary declarations (Souhrnné hlášení) for EU transactions covered by this reporting requirement.
The standard VAT reporting period is monthly. Businesses that meet the legal requirements can use quarterly reporting.
Light VAT Reporting
Light VAT holders:
Submit a VAT return for months when they must declare Czech VAT.
Submit an EU summary declaration when they provide B2B services to companies in other EU countries under the standard place-of-supply rule.
Do not submit Czech VAT control statements.
Do not submit nil VAT returns for months without a Czech VAT declaration obligation.
For example, purchasing Google Ads can require a Light VAT holder to submit a VAT return and pay Czech VAT.
Invoicing a German company for consulting services requires an EU summary declaration, but no Czech VAT payment on that invoice.
When Are VAT Reports Due?
VAT returns and EU summary declarations must be submitted by the 25th day after the reporting period ends.
VAT control statement deadlines depend on the type of taxpayer and reporting period.
These rules are covered by §§ 101, 101c and 102 of the Czech VAT Act.
5. How Can You Check Your Czech VAT Registration Status?
Not sure if your Czech business is registered for Full VAT, Light VAT, or not registered for VAT at all?
Pexpats Business Search allows you to check your VAT registration status for free using your business identification number (IČO).
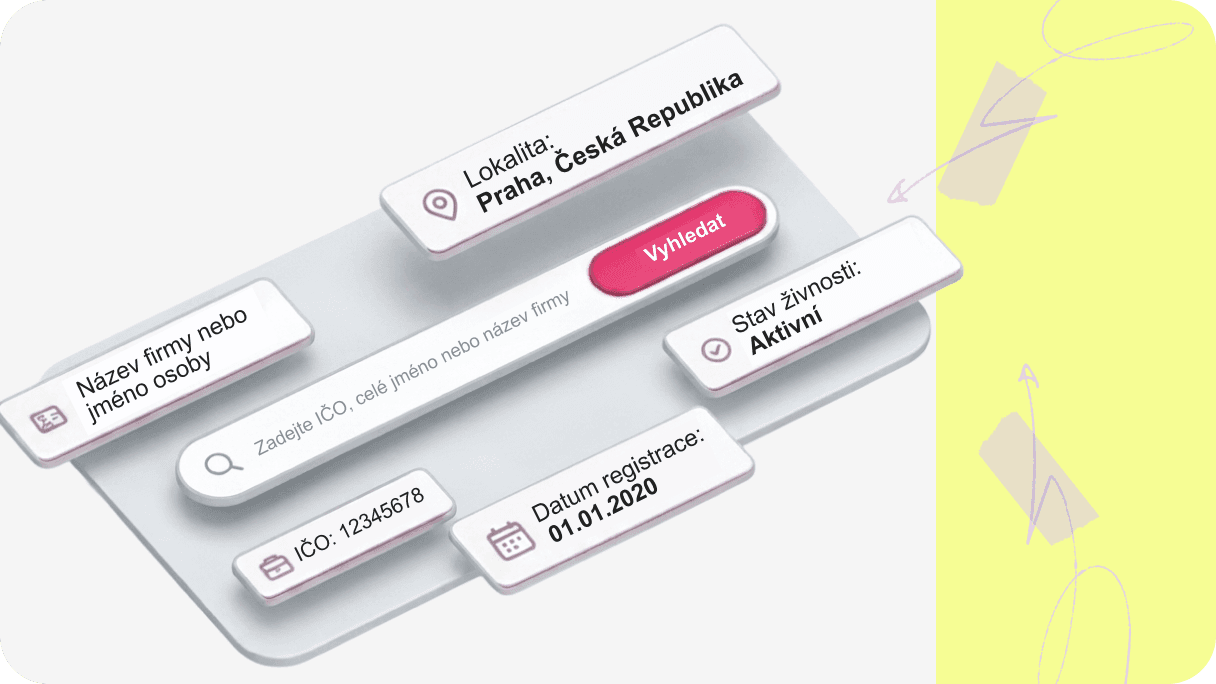
Here is how it differs from other verification tools:
VIES (EU VAT Verification) — Confirms if your VAT number is valid for EU transactions but does not show if you have Full Czech VAT or Light VAT.
ARES (Czech Business Register) — Provides official Czech business information but does not directly show your VAT registration type.
Pexpats Business Search — Shows your business information and clearly identifies if you have Full Czech VAT, Light VAT, or no recorded VAT registration.
This is very useful for freelancers who already have an IČO and DIČ registered but are not sure about their VAT registration status.
Need Help with Czech VAT?
Pexpats is a certified tax and accounting agency in the Czech Republic. We help freelancers and businesses with Full VAT and Light VAT registration, VAT cancellation, and VAT declarations.
Already having problems with the Czech tax authority?
Pexpats can take over existing VAT issues, including incomplete registrations, rejected applications, missing declarations, or can help with appeals. We communicate with the tax authority and work to resolve these problems on your behalf.
Our services are 100% online. Simply complete our online form and electronically sign a power of attorney. Pexpats handles the entire process, including communication with the Czech tax authority, without requiring you to manage the paperwork yourself fully on your behalf.